All Categories
Featured

Integrating Life Insurance With Care Planning
Table of Contents
We're sorry, however we were not able to authorize your demand. Please call us at 800-433-9196 and offer reference number SWAF-18. d31c2117.1789333798.3 d6b4154. We excuse any trouble. 0915-82LR
Just like how cereal can be a part of a well balanced breakfast, life insurance coverage can be part of a balanced and holistic retirement preparation method; nevertheless, the first obstacle to overcome when thinking about whether life insurance can be leveraged in your clients' planning is the public's waning understanding on the subject.
1Public understandings on life insurance coverage are typically at odds with reality, especially among more youthful generations: just 36% of Gen Z individuals own life insurance coverage, with rates usually increasing by age in spite of the energy of policies at any phase of life and the reality that such a space leaves more youthful Americans distinctively susceptible to life's unpredictabilities.
Integrating Life Insurance and Care Planning
1With retirement planning growing more complicated and diy each year, your customers thinking about retirement need all the earnings sources they can get. But should life insurance be one of those services? And how can monetary specialists appropriately leverage it? On paper, life insurance coverage is often simplistically comprehended as a death benefit: several people receiving settlement in the form of cash upon the death of another person to spend for expenses, supplement enduring loved ones, and other requirements.
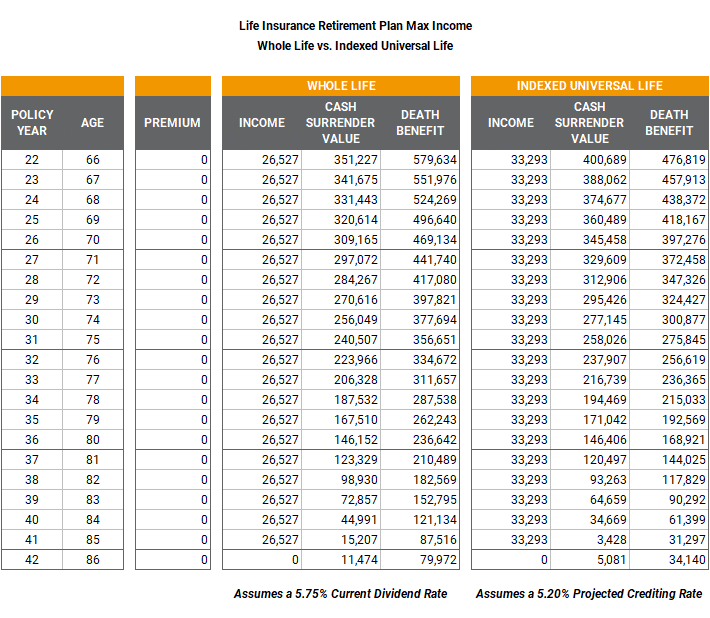
Much of this strategy pertains to leveraging cash value life insurance coverage: a type of life insurance coverage that policy holders pay cash into over time to build worth, similar to a 401(k) or individual retirement account and which they can later make withdrawals from mainly tax-free. Such policies typically have higher premiums for holders, and it holds true that taking out too much money can ultimately deplete survivor benefit, but professionals state with appropriate management, clients actually can have their cake and consume it, too.
"In some methods, these policies can do not simply double responsibility, however triple responsibility for the retiree. If using a money value policy with a long-lasting care (LTC) or persistent illness rider, that agreement can supply tax-free retirement income for the healthy retiree, be a source of needed earnings for the retiree who sustains a long-lasting care occasion, and still eventually pay a tax-free death advantage to heirs."Paul Wetmore, MBA, LUTCF, CLU, FSCP, an adjunct teacher of insurance at The College, concurred with Parrish that utilizing life insurance can really reduce pressure on a customer's other retirement planning possessions and allow them to carry out much better in time."For instance, a customer without the hybrid life/LTC policy might need to have more assets allocated for an unanticipated need and be required to keep them reserve in something underperforming possibly not in money, however something low-risk and very liquid," he stated.
Retirement Planning Orange CAComprehensive Senior Financial Strategy for 2026
There's even a term for it: Life Insurance Retirement Strategy, or LIRP for brief. Regardless of popular understanding, it's frequently great to motivate clients to purchase life insurance young so they can continue to pay into it as they age. That stated, even with clients already in retirement, life insurance coverage can still be an important investment.
"In the second, tax-free life insurance is far more effective as a tradition automobile than leaving IRAs, 401(k)s, and other taxable accounts. Cash worth life insurance can be a beneficial tool for securing a tax-favored source of retirement income that can assist supplement other sources of retirement earnings and bridge Social Security.
"Keep in mind that more likely than not, the retiree's kids will be acquiring their moms and dads' wealth when the children are in their peak earning years and possibly in a high tax bracket. Research has actually shown that when senior citizens leave a recognized legacy rather than simply leaving whatever is left over, they are better in retirement.
How Retired Adults Plan for Rising Care Expenses
1 Nerdwallet - Is Whole Life Insurance a Good Investment in 2026? 2 Nerdwallet - What Is the Life Insurance Coverage Death Benefit? 3 USNews - What Is a Life Insurance Retirement Strategy (LIRP)?

Latest Posts

Practical Preparation for LTC Care in 2026

How to Plan for 2026 LTC Costs

Navigating Future Medical Rates in 2026