All Categories
Featured


Navigating Future Medical Rates in 2026
Table of Contents
If you're unable to leave your home for medical or therapeutic care, Medicare will pay for home health care services. It can consist of a range of advantages for individuals who need continuous medical attention and/or custodial care with everyday activities like consuming, bathing, or mobility in facilities from assisted living to full-time, in- home custodial care to a personal space in a nursing facility.
The expense of a long-term care policy is based upon age, wanted benefit amount and any fringe benefits you select to consist of. That's why it's important to identify your long-lasting care requirements and level of defense before it becomes an emergency situation. Considering long-term care is a cornerstone in any monetary strategy, and there are many alternatives to pick from based upon your monetary circumstance and needs.
It's much better to be overprepared and covered, than underprepared and economically devastated.
Medicare does not cover your long-term nursing care or 24/7 in-home services, nor does it pay for your custodial care which includes your everyday activities such as consuming, bathing, and dressing.
Projecting 2026 Long-Term Care Expenses
Why do many monetary consultants inform clients they can self-insure for long-term care however advise them to buy additional coverage to Medicare? This concern has pestered me for thirty years. The main factor this topic is so important is that the most common objection my team and I experience regarding long-term care insurance coverage is, "I'm going to self-insure." Numerous people genuinely want the defense of insurance coverage, yet their monetary advisor often suggests that self-insurance is more suitable.
They consistently buy Part D drug protection, either coupled with Medicare Benefit or a conventional Medicare supplement. Financial consultants seldom recommend versus purchasing additional Medicare protection. In fact, just 6% of Medicare recipients lack any extra protection. 1 Existing research indicates that the typical Medicare Supplement premium is approximately $2,600 annually.
The typical claim payment is significantly less than $4,000 annually, according to Telos Actuarial. For 2026, there is a $2,100 cap on drug coverage under Part D. If you do not believe me that the claim payments are small, take a look at the Description of Advantages that reveals the claim payments from your Medicare Supplement or Part D drug plan.
Females who need care more than a year average 4.7 years. Male who need care more than a year typical 3.8 years.
5 If you thought there was just a 20% opportunity your home wouldn't be damaged, would you cancel your house owner's insurance? Some people maintain Medicare extra coverage because they mistakenly think Medicare will cover their long-lasting care costs. The most current study from Nationwide's Retirement Institute reports that 58% of U.S.
Choosing the Right Annuity for Care
6 It works as medical insurance to assist individuals recovering from health problem or injury, however does not cover most in-home care, nursing home stays, or services at assisted living facilities. Plan G, the most popular Medicare supplement plan, covers 100% of Part B coinsurance and Part A deductibles/coinsurance after the yearly Part B deductible ($283 in 2026) is paid.
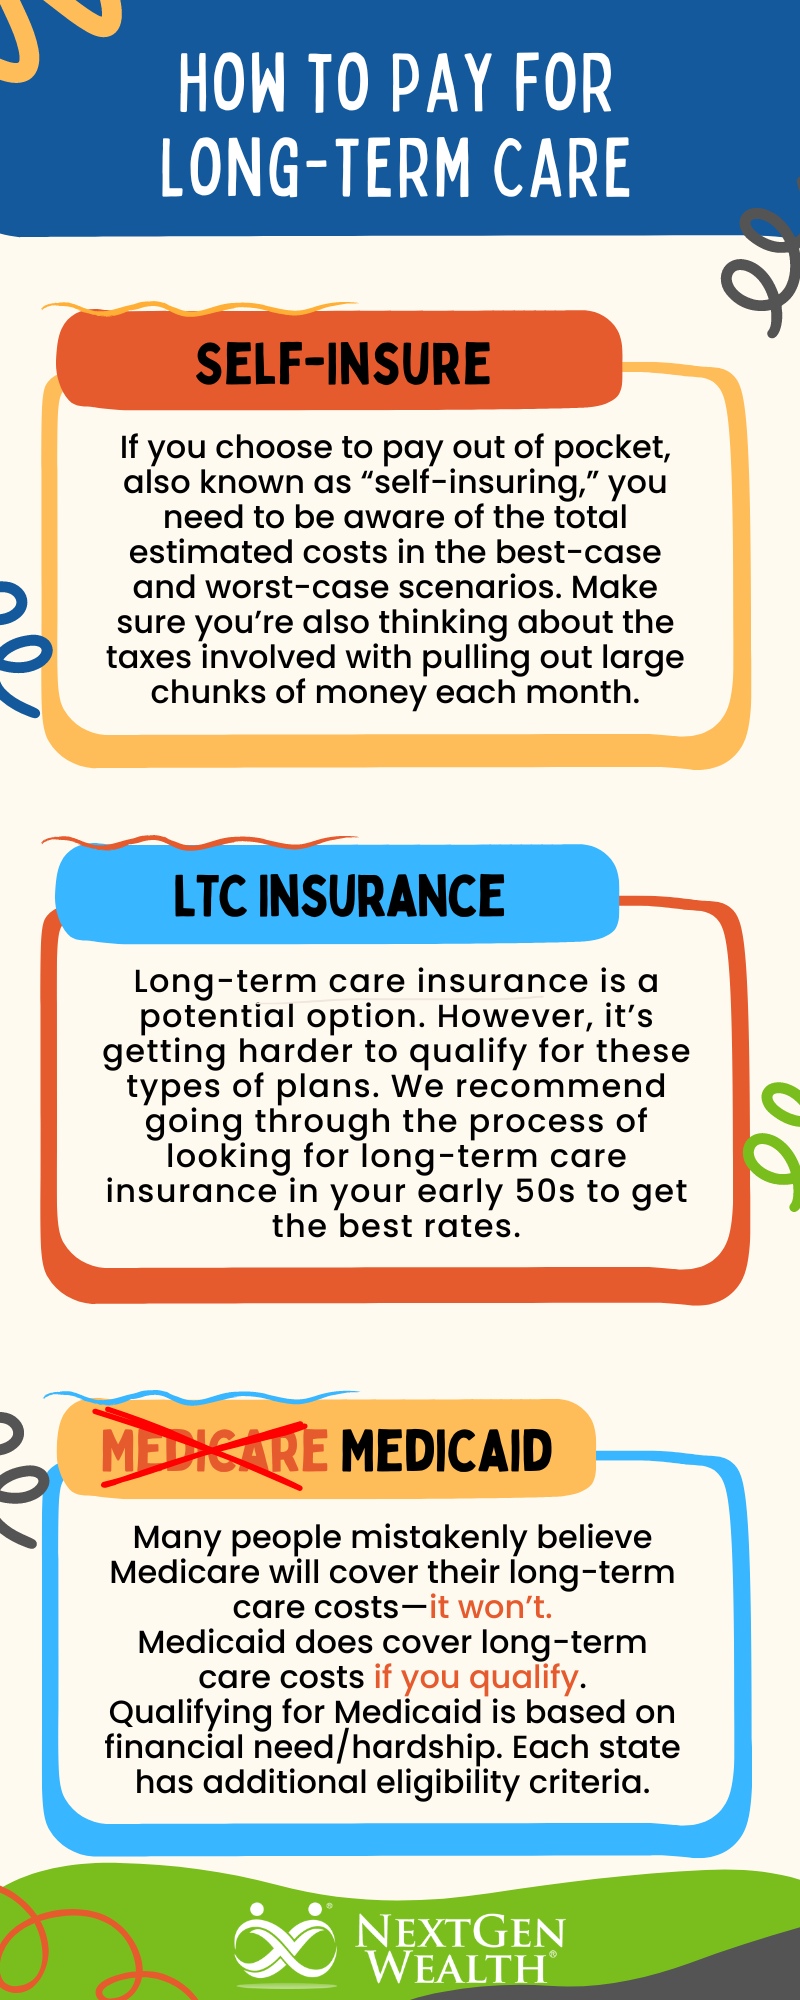
This brings us back to retirement savings. Suze Orman simply recommended someone with $4 million in retirement cost savings NOT to self-insure for long-lasting care. Listen to Suze's recommendation listed below: The Center for Research Study at Boston College found that only 20% of senior citizens will not require long-term care, while another 20% are likely to experience a severe requirement.
After hours of customizing a strategy to a client's budget, it can be undermined by a single email from a monetary advisor. Long-Term Care insurance coverage provides you numerous more dollars in advantages vs.
Why to Secure Critical Illness Insurance
Ladies who need care more than a year typical 4.7 years. Male who require care more than a year typical 3.8 years.
5 If you thought there was only a 20% possibility your home wouldn't be ruined, would you cancel your house owner's insurance? Some people keep Medicare extra coverage since they mistakenly believe Medicare will cover their long-term care expenditures. The newest survey from Nationwide's Retirement Institute reports that 58% of U.S.
Retirement Planning San Diego CA6 It functions as medical insurance to help individuals recovering from illness or injury, but does not cover most in-home care, nursing home stays, or services at nursing home. Strategy G, the most popular Medicare supplement plan, covers 100% of Part B coinsurance and Part A deductibles/coinsurance after the yearly Part B deductible ($283 in 2026) is paid.
This brings us back to retirement savings. Suze Orman just advised somebody with $4 million in retirement savings NOT to self-insure for long-lasting care. Listen to Suze's suggestion listed below: The Center for Research Study at Boston College found that just 20% of retirees will not require long-term care, while another 20% are most likely to experience an extreme need.
After hours of customizing a plan to a client's budget, it can be weakened by a single e-mail from a financial advisor. Long-Term Care insurance coverage provides you numerous more dollars in advantages vs.

Latest Posts

Practical Preparation for LTC Care in 2026

How to Plan for 2026 LTC Costs
Navigating Future Medical Rates in 2026