All Categories
Featured


Understanding LTC Insurance Versus Medicare
Table of Contents
If you're not able to leave your home for medical or therapeutic care, Medicare will spend for home healthcare services. Significantly, Medicare will not cover 24-hour care. Long-lasting Care (LTC) Insurance coverage is created to cover long-term services and assistance not covered by conventional medical insurance or Medicare. It can consist of a variety of benefits for individuals who need constant medical attention and/or custodial care with day-to-day activities like eating, bathing, or movement in facilities from assisted living to full-time, in- home custodial care to a personal space in a nursing center.
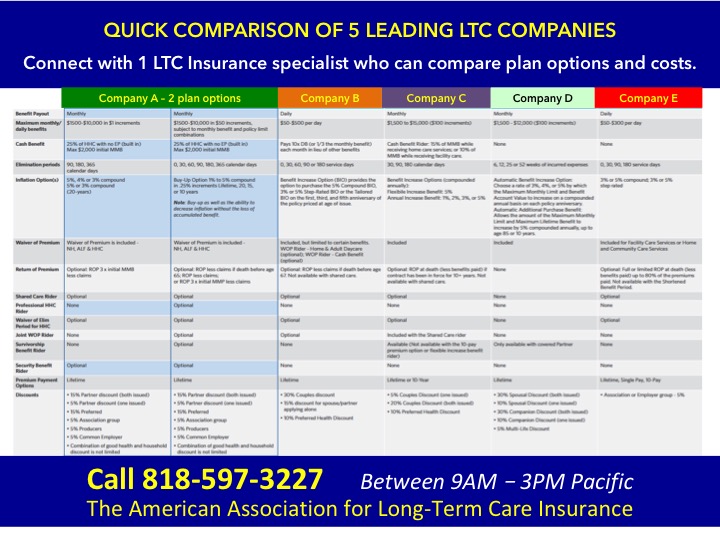
The expense of a long-term care policy is based on age, wanted benefit amount and any additional advantages you select to consist of. That's why it is very important to identify your long-term care requirements and level of security before it becomes an emergency. Considering long-term care is a foundation in any monetary plan, and there are numerous options to select from based on your monetary scenario and needs.
It's better to be overprepared and covered, than underprepared and economically ravaged.
Medicare does not cover your long-term nursing care or 24/7 at home services, nor does it spend for your custodial care that includes your day-to-day activities such as eating, bathing, and dressing.
Income Planning With Life Insurance Vehicles
Why do many financial consultants tell customers they can self-insure for long-lasting care but encourage them to buy additional protection to Medicare? Many people really desire the protection of insurance, yet their financial advisor typically suggests that self-insurance is preferable.
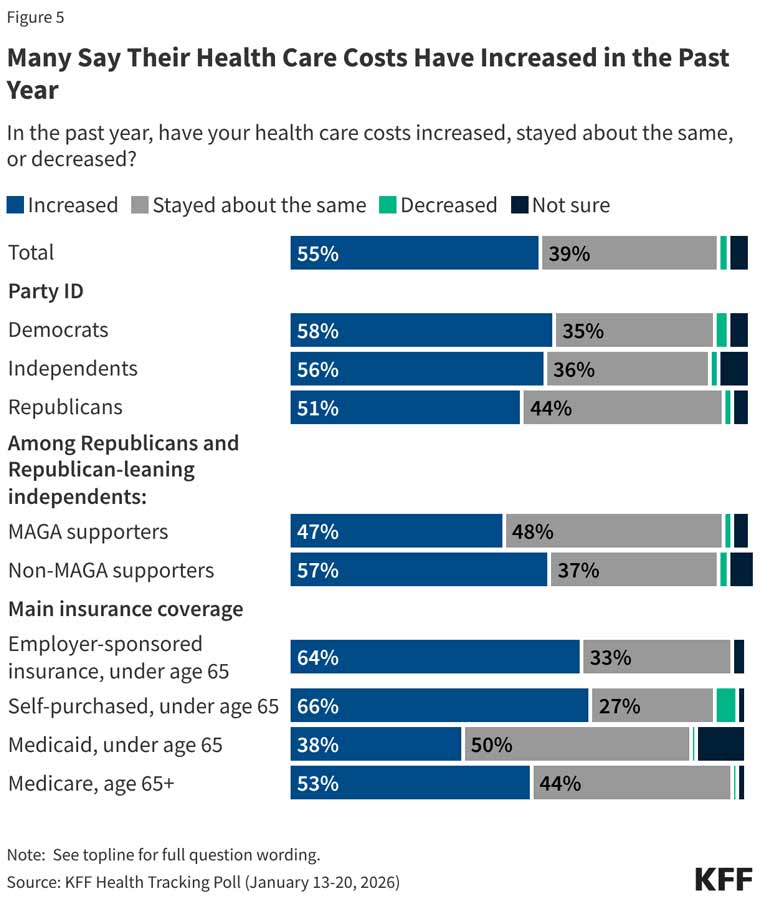
They consistently buy Part D drug coverage, either combined with Medicare Benefit or a traditional Medicare supplement. Financial consultants rarely recommend versus buying additional Medicare coverage. Only 6% of Medicare recipients lack any additional protection. 1 Present research shows that the typical Medicare Supplement premium is approximately $2,600 every year.
The average claim payment is substantially less than $4,000 annually, according to Telos Actuarial. For 2026, there is a $2,100 cap on drug coverage under Part D. If you do not believe me that the claim payments are small, take a look at the Explanation of Advantages that reveals the claim payments from your Medicare Supplement or Part D drug plan.
Ladies who require care more than a year average 4.7 years. Men who need care more than a year typical 3.8 years.
Some individuals maintain Medicare extra protection due to the fact that they wrongly think Medicare will cover their long-lasting care expenses. The most current study from Nationwide's Retirement Institute reports that 58% of U.S.
6 It functions as works insurance to insurance coverage individuals help from illness or injury, but does not cover most in-home careAt home nursing home stays, or services at assisted living facilities.
This brings us back to retirement savings. Suze Orman just encouraged someone with $4 million in retirement savings NOT to self-insure for long-lasting care. Listen to Suze's recommendation below: The Center for Research at Boston College discovered that only 20% of retirees will not need long-lasting care, while another 20% are most likely to experience an extreme requirement.
There are more choices offered now than ever previously. After hours of customizing a strategy to a customer's budget, it can be undermined by a single e-mail from a financial advisor. Typically, I fear their inspiration is to maintain properties under management. Before taking the suggestions of a monetary advisor telling you to self-insure long-lasting care, please do 2 things: Send the consultant to my list of questions here: Click this link for a no responsibility consultation with a member of my expert and well-informed team: You may very well be able to self-insure, but do you really desire to? Long-Term Care insurance offers you a lot more dollars in advantages vs.
How to Secure Critical Illness Insurance
Females who need care more than a year average 4.7 years. Male who need care more than a year typical 3.8 years.
5 If you believed there was only a 20% possibility your home would not be ruined, would you cancel your house owner's insurance coverage? Some individuals preserve Medicare supplemental coverage since they erroneously believe Medicare will cover their long-term care costs. The most recent study from Nationwide's Retirement Institute reports that 58% of U.S.
Retirement Planning Anaheim CA6 It functions as medical insurance to assist individuals recovering from disease or injury, but does not cover most at home care, nursing home stays, or services at assisted living facilities. Plan G, the most popular Medicare supplement strategy, covers 100% of Part B coinsurance and Part A deductibles/coinsurance after the annual Part B deductible ($283 in 2026) is paid.
This brings us back to retirement savings. Suze Orman just advised somebody with $4 million in retirement cost savings NOT to self-insure for long-lasting care. Listen to Suze's recommendation below: The Center for Research Study at Boston College found that just 20% of retired people will not need long-term care, while another 20% are most likely to experience an extreme requirement.
There are more choices readily available now than ever in the past. Nevertheless, after hours of customizing a plan to a client's budget, it can be weakened by a single e-mail from a financial advisor. Often, I fear their inspiration is to retain properties under management. Before taking the advice of a monetary consultant telling you to self-insure long-lasting care, please do 2 things: Send out the consultant to my list of questions here: Click this link for a no responsibility consultation with a member of my expert and well-informed team: You may very well be able to self-insure, but do you actually wish to? Long-Term Care insurance gives you many more dollars in advantages vs.

Latest Posts

Why to Prepare for Upcoming Long-Term Care Expenses
Why Seniors Can Benefit From Accident Insurance
Projecting 2026 LTC Expenses